The US$1.2 trillion bet that AI pays on time
AI may live up to the technological hype while disappointing investors. Vast infrastructure spending is being financed on fixed schedules even as returns remain uncertain and hardware ages quickly.
The AI build-out has been financed with money that demands dates, and investors may see poor returns even if the technology transforms the economy.
Like the canal mania and railways boom of centuries past, artificial intelligence (AI) can transform the economy but still produce poor returns for the investors financing its build-out.
Companies may find and implement valuable uses for generative AI, but the assets supporting those uses can reach the end of their economic lives before the resulting cash flows have covered the investment, while debt service continues on fixed dates.
In other words, the case for the technology and the case for the investment are not the same.
US Securities and Exchange Commission filings show Microsoft, Alphabet, Amazon, Meta and Oracle put US$413.2 billion into capital expenditure in their latest financial years against depreciation of US$110.6 billion.
That wedge, US$302.6 billion, equals 78 per cent of their combined net income of US$389.3 billion. It runs from 42 per cent of net income at Microsoft to 281 at Oracle, now rated BBB minus, the lowest investment-grade tier. Nvidia, the vendor rather than a buyer, is the control: its wedge is 3 per cent.
A dollar of capital expenditure is immediate revenue for the seller, but an expense recognised by the buyer over years.
AI-related borrowers have sold US$218 billion of investment-grade bonds in the US market this year to 8 July, against US$80.5 billion for all of 2025. By October 2025, PitchBook LCD estimated AI-linked debt outstanding at about US$1.2 trillion, the largest sector of the US investment-grade bond market at 14 per cent, ahead of banks at 11.7 per cent.
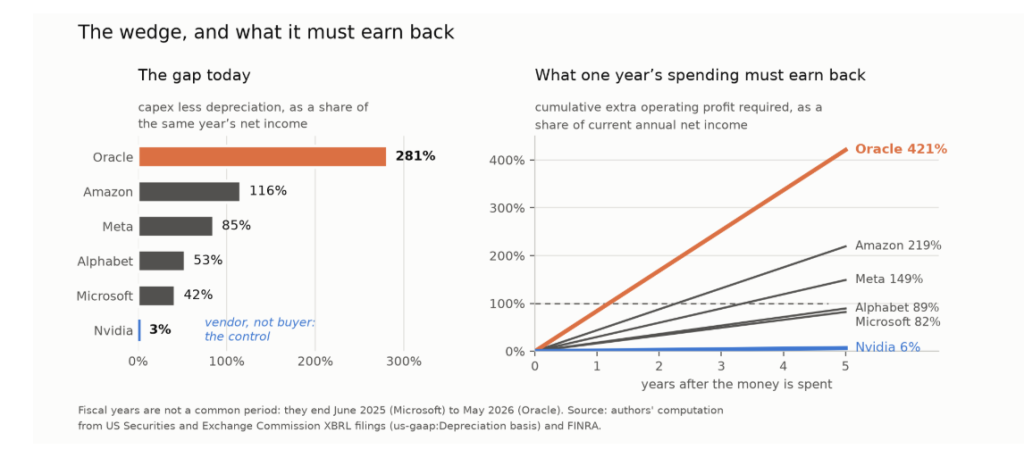
Chart 1. Panel A: capital expenditure less depreciation as a share of the same year’s net income, latest reported financial years. Panel B: cumulative extra operating profit one year’s capital spending would need to earn in a common five-year stress calculation, using a five-year life Amazon reports for some servers and networking equipment, and the 5.844 per cent observed yield on Oracle’s 2030 notes. This is not a forecast or an estimate of each company’s asset lives or funding costs.
Spending above depreciation is ordinary growth accounting; Amazon ran ratios above two through much of the 2010s without incident. The wedge is tomorrow’s expense booked as today’s asset: it will flow through earnings over the assets’ lives, whether or not new revenue arrives to meet it.
Depreciation and debt service, however, run to schedules. Equity is better suited to that uncertainty because its claim is residual and undated. Debt is safer only to the extent that existing or contracted cash flows can meet fixed payments.
The mismatch is the main risk; the amount compounds it where borrowing is large relative to the cash a business already generates.
Cover on bond offerings from the hyperscalers, the companies building the data centres, fell from nearly five times the offer in February to below two in July. Across US investment-grade issues as a whole, cover slipped about half a point over the same span, so the deterioration was concentrated among these issuers.
Amazon’s surprise US$25 billion sale that month needed 18 to 21 basis points of extra yield on its longest tranches.
Meta priced US$30 billion of senior notes last October at coupons between 4.200 and 5.750 per cent. In the same window Beignet Investor LLC, the vehicle financing the Hyperion data centre in which Meta holds 20 per cent, sold US$27.3 billion of 6.581 per cent senior secured notes due 2049 at 85 to 100 basis points above Meta’s own curve.
The debt finances long-lived data-centre infrastructure, but its cash flows depend on a technology stack that will be replaced several times before the paper matures.
From 1 January 2025, Amazon shortened the estimated useful life of a subset of its servers and networking equipment from six years to five, citing in its annual report “the increased pace of technology development, particularly in the area of artificial intelligence and machine learning”.
The change added US$1.4 billion of annual depreciation and took US$1.0 billion off net income. Amazon took that earnings hit after recognising that faster development in AI and machine learning was shortening the economic life of some equipment.
Four of the five lifted revenue per employee by 38 to 89 per cent between 2022 and 2025 while headcounts were flat or fell. Returns may be arriving, but the accounts do not isolate AI’s contribution.
Capital expenditure takes 47 to 60 per cent of operating cash flow at Microsoft, Alphabet and Meta, 89 at Amazon and 174 at Oracle. Oracle is US$23.7 billion short after investment and US$28.3 billion after interest, before principal or distributions. Interest cover runs from 174 times at Alphabet to 4.5 at Oracle.
These are not one trade. Three could slow spending tomorrow and stay comfortable; Amazon has less room. Oracle cannot fund current spending internally. If the buyers reduce capital expenditure more broadly, pressure transfers to the vendor: Nvidia’s annual revenue equals about half their combined spending.
The coupons fall due before the returns arrive.
Exposure of this kind belongs in claims that can wait, which means equity, or debt sized to the cash a business already generates rather than the direction it is betting on. AI will be transformative, but financially there is a wild ride ahead.
The views expressed in this article may or may not reflect those of Pearls and Irritations.